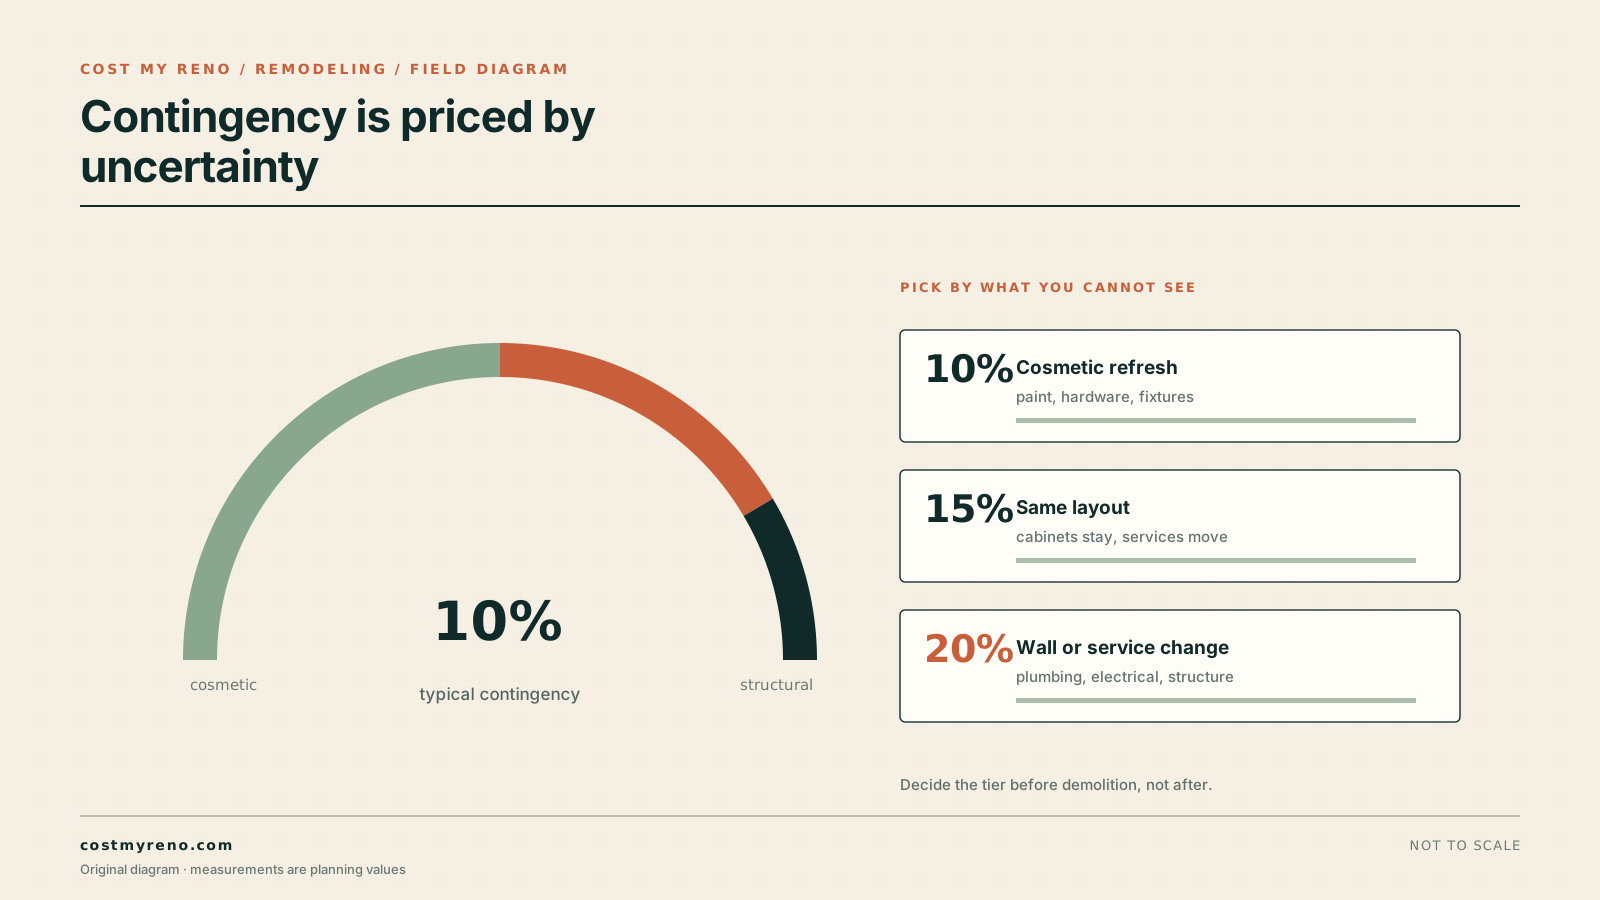
A kitchen reserve is owner-controlled money for what the walls hide. Size it at 8–22% by tier and risk, keep upgrades and allowance overages in separate columns, and release it only against written change orders with prices and schedule impact.
Numbers to plan with
Three Kinds of Uncertainty, and Only One Belongs in the Reserve
A kitchen reserve answers exactly one question: what will the walls hide? Concealed conditions—rotted framing, undersized wiring, a cracked drain, asbestos tile—are why the reserve exists, and they typically consume 5–15% of a mid-range contract. Owner-directed changes are a separate account; if you plan to add a window, move a wall, or upgrade appliances, fund a $3,000–$10,000 upgrade column and leave it alone. Market drift is the third category: a bid is a 30-day snapshot, a 60-day-old cabinet quote can move 3–8%, and an appliance backorder can force a substitution that costs 8–20% more.
The classic failure is spending the reserve in week one. A homeowner approves a $2,400 range upgrade against contingency, demolition reveals a $3,100 cast-iron drain, and the reserve is gone. From that point every discovery becomes a financing decision made under pressure, usually on a credit card at 20–29% APR. Separate the upgrade column and the reserve stays boring—which is exactly what it is for.
Size the Reserve With a Risk Table, Not a Round Number
Start with the project tier, then add points for specific risk signals. On a $64,000 mid-range kitchen, 12% is $7,680. A cosmetic refresh in a post-1990 house can run 8%; a gut remodel with one wall moved in a 1950s house should run 18%. Add 3 points for pre-1980 plumbing or wiring, 3 for slab-on-grade drain work, 2 for prior unpermitted work, 3 for a structural opening, and 2 if key selections are unresolved at signing. Cap the total at 25%, round up to the next $500, and move the money out of the household checking account.
If you are using a rehabilitation loan, the lender may require its own contingency reserve—commonly 10–20% of the repair estimate—and control each release. Ask how that reserve interacts with yours so you are not counting the same dollars twice, and confirm whether unused funds reduce the loan balance or are disbursed to you. On a conventional renovation, the reserve is simply your money; the contract should say who holds it, what it can pay for, and how the remainder is returned at final payment.
Reserve sizing on a $64,000 kitchen. Percentages are planning starting points; adjust with the risk adders above and cap the total near 25%.
| Project profile | Reserve | On a $64,000 budget | What usually triggers a draw |
|---|---|---|---|
| Cosmetic refresh, post-1990 house, no layout change | 8% | $5,120 | Outlet or vent correction, minor patch, one surprise under the sink |
| Replace-in-place, 1970s–80s house, same footprint | 12% | $7,680 | Subfloor repair, one circuit, drain or shutoff replacement |
| Gut remodel, one wall moved, 1950s–60s house | 18% | $11,520 | Relocated drain, obsolete wiring, missing header, exterior-wall insulation |
| Gut plus structural opening and panel replacement | 22% | $14,080 | Engineered header, service upgrade, permit revision, extended schedule |
| Any tier with prior water damage or unpermitted work | +3 points | +$1,920 | Mold remediation, code correction, re-inspection of previous work |
What the Reserve Legitimately Covers, and the Four Things It Never Should
Legitimate draws are specific, unpleasant, and usually discovered between demolition and drywall. Typical 2026 costs: rotted subfloor around a sink or dishwasher $900–$2,800; a failed cast-iron drain under a slab $2,000–$5,500; rewiring two knob-and-tube circuits $1,800–$4,500; a missing or undersized header $3,500–$9,000; asbestos floor tile and mastic abatement in a 120 sq ft kitchen $1,500–$4,500; lead paint stabilization on six window openings $1,200–$3,500; mold behind old cabinets $1,000–$4,000; insulation added to two exterior walls $700–$1,800. Environmental work is the genuine exception to the visible-scope rule because it is rarely visible and carries regulated work practices.
Four items do not belong in the reserve: an upgrade you chose, scope that was visible in the original walkthrough, the contractor's arithmetic error, and permits or tax that were always required. The test is a $400–$900 pre-demolition inspection—plumber's camera, electrician's panel review, carpenter opening one wall. If that inspection could have seen it, it belongs in the base budget. Moving it into the reserve does not make the budget complete; it just hides an omission until the week you can least afford it.
Allowance Overage Is a Budget Line, Not a Reserve Draw
Allowances and contingency solve different problems, and mixing them is how a healthy reserve disappears on tile. Take a $4,500 countertop allowance over 45 sq ft: that is $100 per sq ft. Choose quartz at $118 per sq ft installed and the real cost is $5,310, an $810 overage before tax. Add 8% tax on the difference and the draw is about $875—11% of a $7,680 reserve—spent on a known selection, not an unknown condition. The overage belongs in the finish budget, funded by cutting another allowance, not in the reserve.
Set allowances by shopping before you sign. Get three quotes at the level you actually like, then write the middle selection's price into the contract rather than the entry price. A useful rule is the 60th–70th percentile of what you would genuinely choose, because an allowance set at the cheapest option guarantees an overage. Confirm how overages are billed—at cost plus 15–25% or at retail—and set the selection deadline 10 business days before the order date. The named failure is the late stone choice: cabinets ordered, template blocked, 2–3 weeks lost, and $250–$500 spent on temporary counters.
A Change-Order Procedure With Dollar Thresholds
Every draw needs five fields before work proceeds: a photo and dimensions of the condition, a fixed price or unit price with tax, the schedule impact in working days, the funding source, and an approval signature. Set thresholds in the contract. Under $500, the owner can authorize by phone with same-day email confirmation. From $500 to $2,500, a signed written change order is required before work starts. Above $2,500, add a revised schedule and, on a financed job, lender notification. For immediate safety work—an active leak, exposed conductors—allow up to $1,500 with a written follow-up within 24 hours.
Ban the sentence we will square up at the end. It converts a controlled reserve into an open account, and it makes lien waivers and final payment impossible to reconcile. Keep a ledger with columns for change-order number, date, description, amount, schedule days, funding source (reserve, upgrade, or allowance), and remaining balance. Require each invoice to reference the change-order numbers it bills, and release progress payments only against completed milestones—not against a percentage of the reserve.
- Reserve draw: concealed condition, priced and photographed before work.
- Upgrade draw: owner-chosen change, funded from a separate column.
- Allowance overage: known selection above the contract allowance, funded by scope trade-offs.
- Contractor error: corrected at the contractor's cost, not from the owner's reserve.
Track Three Numbers Weekly and Re-Plan at 50 Percent
Track original reserve, committed dollars, and uncommitted balance once a week, on one page. Take the $7,680 reserve: week two brings a $1,450 subfloor repair and a $3,100 drain replacement, so committed is $4,550 and remaining is $3,130—41% left before rough-in is finished. That is the trigger point. When more than half the reserve is committed before the rough-in inspection, stop and re-plan: revisit allowances, confirm the appliance package, and decide which discretionary items move to a later phase.
Write the scope-reduction list before you need it, with real numbers. Deferring the backsplash saves $2,000–$4,500; reusing the existing refrigerator and range saves $3,000–$6,000; refacing lowers instead of replacing them saves $3,500–$8,000; refinishing existing hardwood instead of new flooring saves $1,500–$4,000; painting existing trim instead of replacing it saves $800–$2,000. Add schedule float as well: 10% of the duration, or about one week on a 10-week job. A reserve without a reduction list becomes a negotiation; a reserve with one becomes a decision you already made calmly.
Close It Out: Holdback, Punch List, and the First-Year Fund
Hold back 5–10% of the contract until the punch list is complete and the final inspection passes—$3,200–$6,400 on a $64,000 job. Release progress payments against milestones such as rough-in inspection, cabinet delivery, and counter template, never against demolition. At closeout, collect lien waivers from every supplier and subcontractor, confirm the final inspection card, register appliance warranties in your name, and keep the permit record with the closing documents. A 30-day walkthrough catches installation defects while the contractor is still motivated; an 11-month walkthrough catches the slow leaks before the workmanship warranty expires.
Expect roughly 2% of the budget, or $1,280 on this kitchen, for first-year adjustments: a sticking drawer, a failed disposal, a caulk joint that opens. Fund it separately rather than reaching into the reserve. If money remains in the reserve at closeout, do not spend it on a spontaneous week-12 upgrade; either return it to savings, apply it to the loan principal, or move it to a written Phase 2 list with quotes. On a credit card at 24% APR, an $8,000 overage carried for a year costs about $1,900 in interest—more than the backsplash you deferred. The reserve is not a budget to use up; it is the reason the rest of the budget can be decided without panic.
Questions that come up on this job
Is 10% contingency enough for a kitchen remodel?
Only for a cosmetic refresh in a documented newer home. A replace-in-place mid-range kitchen needs 12–15%, and a gut with a moved wall, slab plumbing, or a 1950s electrical system needs 18–22%. The reserve tracks uncertainty, not project size: a $200,000 gut with original cast-iron drains can burn 20% on three discoveries, while a $25,000 refresh with a recent panel upgrade may never touch 8%.
Does unused contingency go to the contractor?
No, unless the contract says so in plain language. Contingency is owner money held for owner risk; a contractor's overhead and profit is a different line, typically 15–25%, priced into the base contract. Put one sentence in the agreement: unspent contingency is credited or refunded at final payment, and the owner approves every draw in writing. If a contractor insists the reserve is their fee, you are looking at a cost-plus arrangement—price it that way and compare it to fixed-price bids.
Can I use contingency for an upgrade I decide on mid-project?
Technically you can move money between columns, but it defeats the purpose. A $2,400 range upgrade drawn from a $7,680 reserve leaves $5,280 for real discoveries, and one $3,100 drain replacement puts the job into overage. Decide upgrades before signing and fund them from a separate $3,000–$10,000 column. If you must reallocate mid-job, do it in writing, cut an equal amount from another finish, and record the new reserve balance the same day.
Does homeowners insurance cover hidden damage found during a remodel?
Usually not when the cause is wear, corrosion, rot, or long-term leakage, and most policies exclude code upgrades and faulty workmanship. A sudden event—a pipe that bursts during demolition—may be covered, but the resulting access and patch work often is not. Ask your insurer before demolition, in writing, what a discovered leak or mold finding would require, and keep photos and receipts from the day of discovery.
Sources & further reading
References behind this guide
These sources support the safety, measurement, or industry conventions used above. Product instructions, approved plans, and local requirements control your project.